
By Marc Gilman
Questions? Call (800) 927-9326 or email
Key Takeaways
-
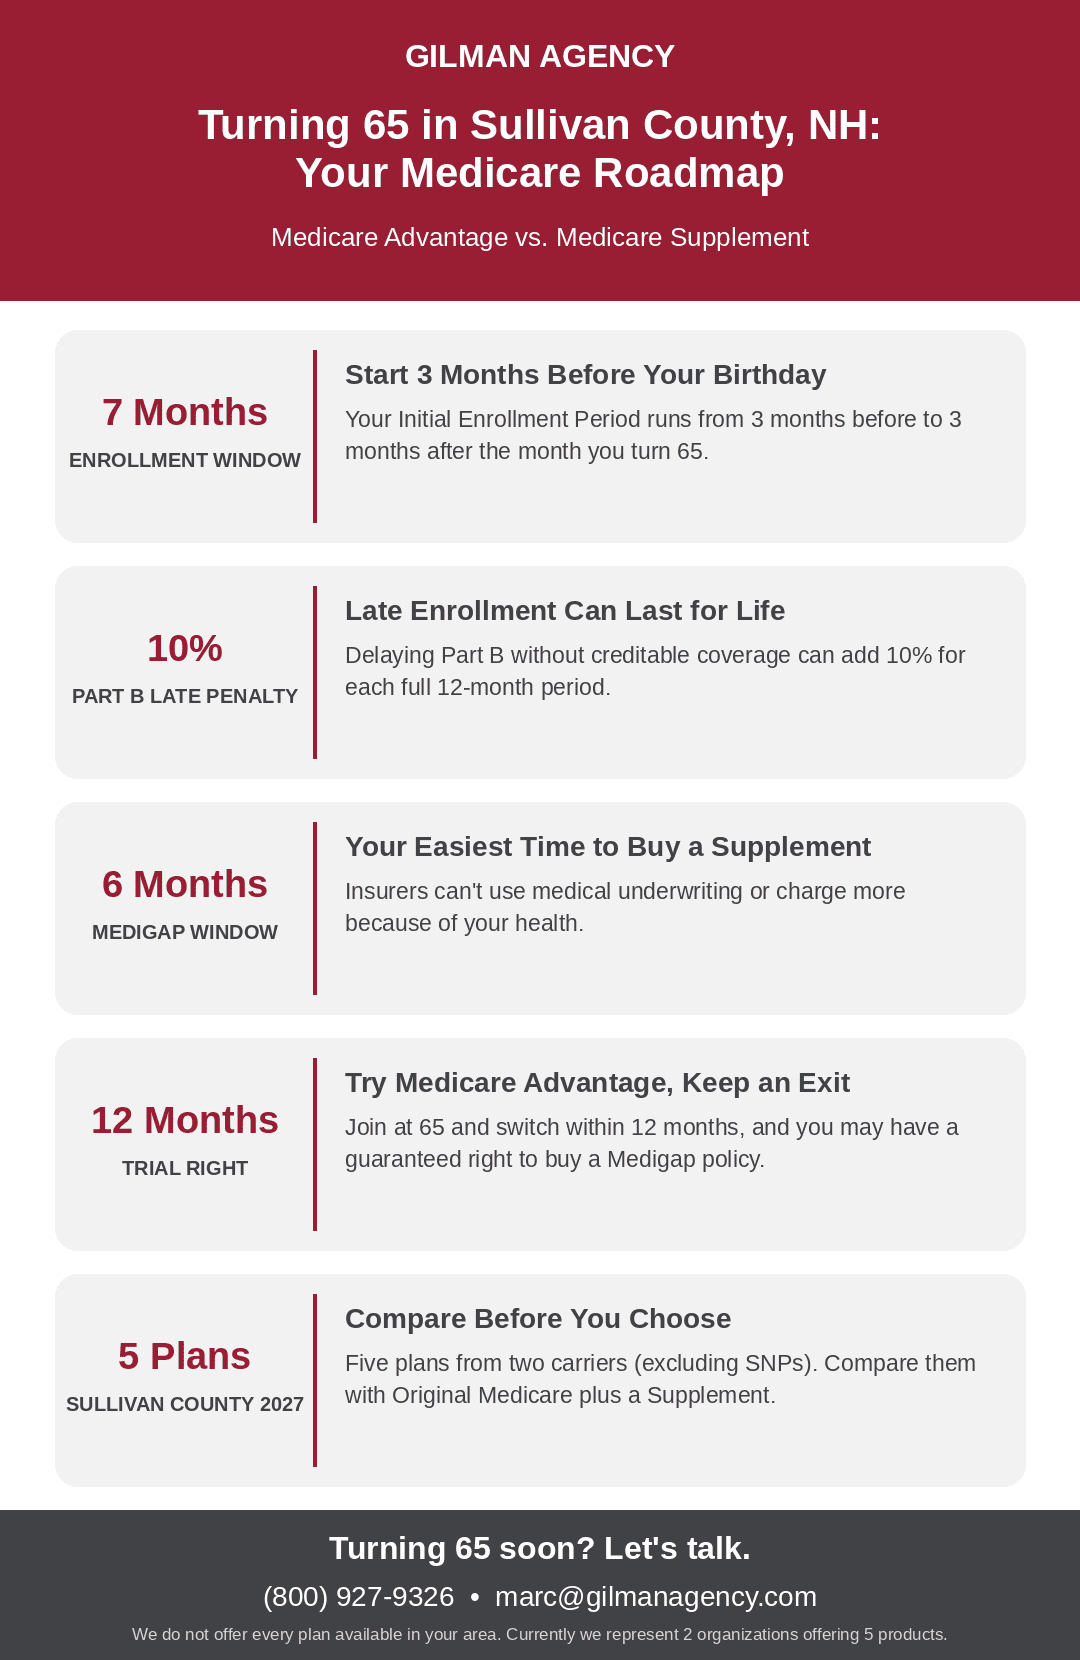
Your Initial Enrollment Period is seven months: the three months before the month you turn 65, your birthday month, and the three months after. Signing up early avoids gaps and late penalties.
-
Your first big choice is Original Medicare with a Medicare Supplement (Medigap) and a Part D drug plan, or a Medicare Advantage plan that bundles coverage.
-
Your Medigap Open Enrollment Period is a one-time, six-month window that starts when you are 65 or older and enrolled in Part B. During it, insurers cannot use medical underwriting or charge more because of your health.
-
If you join Medicare Advantage when you first become eligible, you have a 12-month trial right to switch to Original Medicare and buy a Medigap policy.
-
In Sullivan County, Medicare Plan Finder shows five Medicare Advantage plans from two carriers for 2027 (not counting Special Needs Plans), a mix of HMO and PPO options. Compare them with Original Medicare plus a Supplement before you decide.
Your Enrollment Window: Don’t Wait Until Your Birthday
Most people sign up for Medicare Part A and Part B during their Initial Enrollment Period:
-
3 months before the month you turn 65
-
The month you turn 65
-
3 months after the month you turn 65
If you sign up before your birthday month, Part B coverage generally starts on the first day of the month you turn 65 (or the month before, if your birthday is on the first). If you wait until your birthday month or later, coverage can start later, which may leave a gap.
If you do not have creditable coverage through current employment and you delay Part B, you may face a lifelong late-enrollment penalty of 10% for each full 12-month period you could have had it. Part D has its own late-enrollment penalty. If you or your spouse are still working and covered by an employer plan, different rules apply, so check before you delay.
The Real Question: One Bundled Plan or Original Medicare Plus Add-Ons?
Original Medicare + Medicare Supplement + Part D. Original Medicare (Parts A and B) covers hospital and medical care. A Medicare Supplement helps pay costs Original Medicare leaves, such as deductibles and coinsurance. You can see any provider in the country who accepts Medicare. Medigap does not include drug coverage, so you add a separate Part D plan.
Medicare Advantage (Part C). A single plan that replaces Original Medicare, usually including drug coverage, with a provider network, copayments and a yearly out-of-pocket maximum.
Top Criteria to Compare
-
Your doctors and hospitals. Confirm every provider you use is in a plan’s network. Ask whether it is an HMO or PPO and how out-of-network care is handled.
-
Where you get care. Many Sullivan County residents get care at hospitals and clinics across the Vermont line or in other parts of New Hampshire, and some split the year between New Hampshire and another state. Ask how any plan covers out-of-state and out-of-network care; HMO plans generally limit coverage to in-network care, while PPO plans allow out-of-network care at higher cost.
-
Prescriptions. Check each medication against the plan’s formulary, pharmacy network and tier costs.
-
Total cost, not just premium. Compare premium, deductible, copayments and the maximum out-of-pocket.
-
Prior authorization. Medicare Advantage plans may require approval before certain services.
-
Flexibility later. Switching to a Medigap policy after your first-year trial right or Medigap Open Enrollment Period ends may involve medical underwriting. Think about this before you choose.
What’s Available in Sullivan County for 2027
-
Medicare Advantage: Excluding Special Needs Plans, Medicare Plan Finder shows five plans from two carriers in Sullivan County for 2027, including both PPO and HMO options. Listed details, with each plan’s monthly premium (you still pay the Part B premium), health deductible, in-network maximum out-of-pocket, and primary care / specialist copays:
-
Devoted Choice 001 NH (PPO): $0 premium, $0 health deductible, $6,800 in-network maximum, $0 / $55 copays
-
Devoted Choice Giveback 002 NH (PPO): $0 premium, $50 health deductible, $8,650 in-network maximum, $0 / $50 copays
-
Devoted Choice Giveback Extras 006 NH (PPO): $0 premium, $450 health deductible, $7,650 in-network maximum, $0 / $50 copays
-
Humana Gold Plus H5619-137 (HMO): $14 premium, $0 health deductible, $6,900 in-network maximum, $0 / $75 copays
-
Humana Gold Plus H5619-185 (HMO): $72 premium, $0 health deductible, $6,700 in-network maximum, $0 / $40 copays
The three Devoted plans are new, so Plan Finder does not yet show a CMS star rating for them; both Humana plans are listed at 4 stars. Three Chronic Condition Special Needs Plans (C-SNPs) are also available. Plan drug deductibles and benefits differ, and details can change, so confirm them in Plan Finder or with us before you enroll.
-
-
Medicare Supplement: More than 20 insurers sell Medicare Supplement plans in New Hampshire. Standardized plans such as Plan G and Plan N have the same basic benefits no matter which company sells them; pricing and underwriting rules differ.
-
Part D: Standalone drug plans can be paired with Original Medicare.
Plans and costs change every year. If your Medicare starts January 1, 2027 or later, review the 2027 options.
Why Timing Matters
-
Medigap Open Enrollment Period: six months, starting the month you are 65 or older and enrolled in Part B. This is the easiest time to buy a Supplement because insurers must sell you a policy regardless of health.
-
12-month trial right: if you join Medicare Advantage when you are first eligible at 65 and, within the first 12 months, decide to switch to Original Medicare, you may have a guaranteed right to buy a Medigap policy. The window generally runs from 60 days before your coverage ends to no more than 63 days after.
-
Annual Enrollment Period: October 15 – December 7 each year, when you can change plans for the following year.
-
If you miss your Medigap Open Enrollment Period, you may need to answer health questions to buy a policy later, unless another guaranteed-issue right applies. New Hampshire law may give you additional rights, so it’s worth a discussion with us.
Why Work With a New Hampshire Agent
Turning 65 means choosing a plan, meeting deadlines you only hit once, and avoiding penalties. A local, independent agent can walk through the choices with you at no cost to you. We have clients in Sullivan County and throughout New Hampshire.
What To Do Next
-
Find your Initial Enrollment Period dates, and aim to start three months before your birthday month.
-
List your doctors, hospitals, medications and pharmacy.
-
Compare Original Medicare plus a Supplement and Part D with the Medicare Advantage plans available where you live.
-
If you or your spouse are still working, confirm how your employer coverage works with Medicare before you delay Part B.
-
Call us: (800) 927-9326 or .
Questions? Call (800) 927-9326 or email
We do not offer every plan available in your area. Currently we represent 2 organizations which offer 5 products in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.


