

By Marc Gilman
Call (800) 927-9326 | Email marc@gilmanagency.com
Updated October 24, 2026
If you live in Keene, Swanzey, Jaffrey, Rindge, Hinsdale, Walpole or elsewhere in Cheshire County, the Medicare Advantage market around you has changed a lot in the past two years. That makes the basic question worth asking again this Annual Enrollment: Medicare Advantage or Original Medicare with a Medicare Supplement (Medigap).
Here’s how the two work, what to weigh, and when you can buy Medigap without health questions.
Key Takeaways
-
Two different structures. Medicare Advantage replaces Original Medicare with a private plan that uses a network. A Medigap policy works alongside Original Medicare and lets you see any provider in the country that accepts Medicare.
-
Cheshire County’s Medicare Advantage market keeps changing. Several carriers left for 2026, and more changes take effect statewide for 2027. Check what’s offered at your ZIP code before December 7.
-
Your hospital matters most. Whether Cheshire Medical Center and the Dartmouth Health doctors you see are in a plan’s network can decide the question for you.
-
Medigap is sold statewide. Plans are standardized by letter, so a Plan G covers the same benefits from every insurer. Premiums vary by insurer and age.
-
Timing matters. If your plan is ending, you may have a short window to buy Medigap without health questions. Outside that window, insurers can usually ask about your health.
Medicare Advantage vs. Medicare Supplement: The Real Question
These aren’t two versions of the same product. They’re two different ways of getting your Medicare benefits.
Medicare Advantage (Part C) is offered by a private insurance company approved by Medicare. It replaces Original Medicare for your hospital and medical care, and most plans include drug coverage. You generally use the plan’s network of doctors and hospitals, and you pay copays or coinsurance as you use care.
Original Medicare with a Medicare Supplement (Medigap) keeps Original Medicare as your coverage. A Medigap policy, sold by a private insurer, pays some or all of the deductibles and coinsurance Original Medicare leaves you to pay. You add a separate Part D plan for drugs.
Neither is better for everyone. The right choice depends on your doctors, your health, how much you travel, and how you prefer to budget.
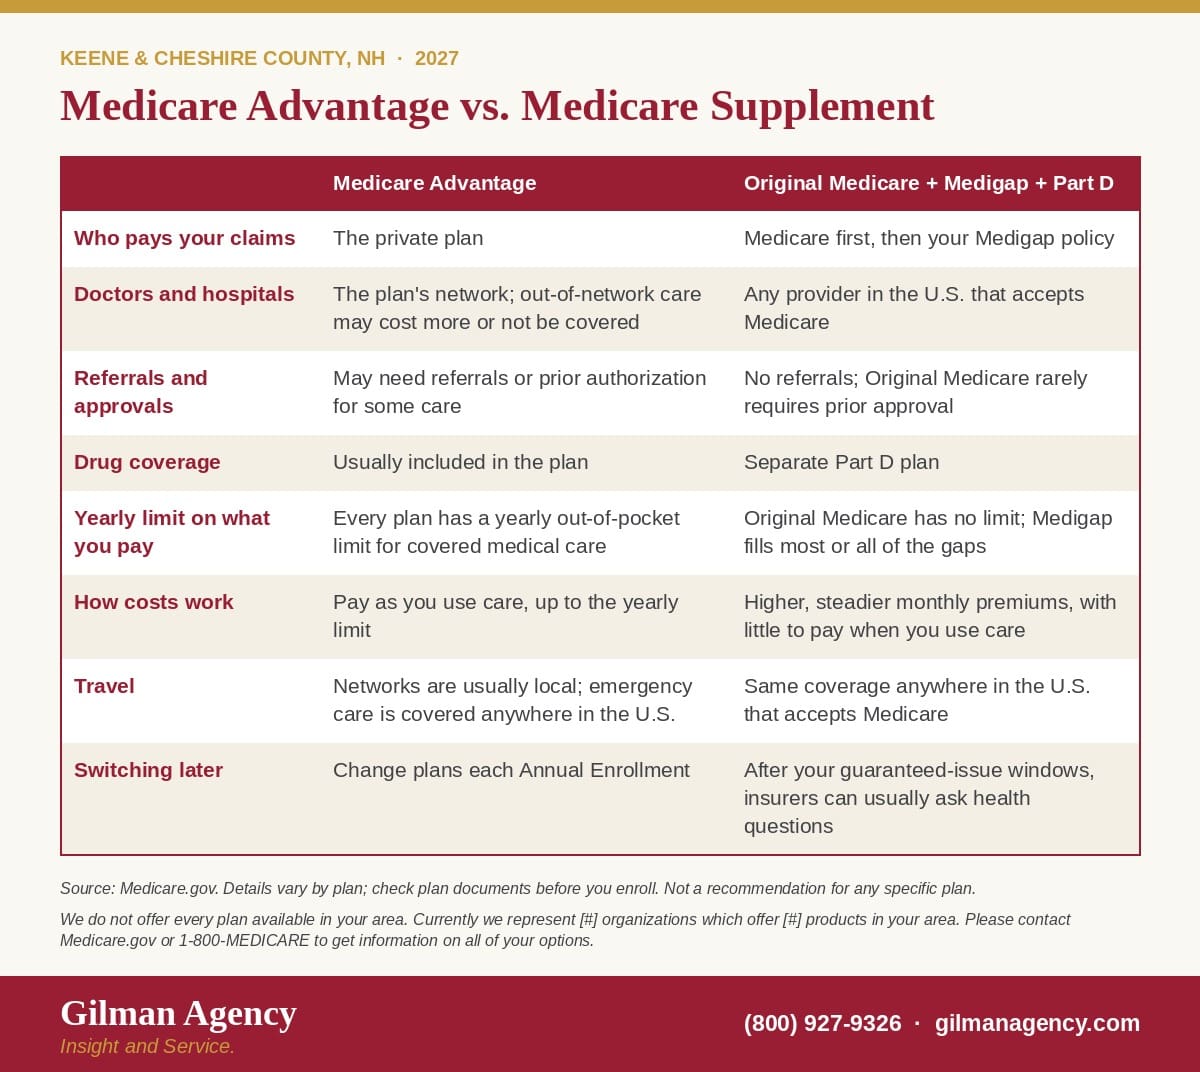
Source: Medicare.gov. Details vary by plan; check plan documents before you enroll.
Top Criteria for Comparing the Two
1. Your doctors and your hospital. In Keene, this usually means Cheshire Medical Center and the Dartmouth Health doctors connected to it. Medicare Advantage network contracts with hospitals can change from year to year, so check by name that your primary care doctor, specialists and hospital are in any plan you consider. Also check any hospital you travel to for specialty care, such as Dartmouth Hitchcock Medical Center in Lebanon or providers in Brattleboro, Vermont. With Original Medicare and Medigap, any of them that accept Medicare work.
2. How predictable you want your costs to be. Medicare Advantage costs depend on how much care you use, up to the plan’s yearly limit. Medigap has a higher monthly premium but leaves little to pay when you need care, so a heavy-use year costs about the same as a light one.
3. Your prescriptions. Medicare Advantage usually includes drug coverage. With Medigap you add a separate Part D plan. Either way, check that each of your drugs is covered and which pharmacy to use.
4. Travel and time away. If you spend winters elsewhere or see specialists in Vermont or Massachusetts, a network can matter. Original Medicare with Medigap works the same anywhere in the country with providers that accept Medicare.
5. Your ability to switch later. You can change Medicare Advantage plans each Annual Enrollment. Moving into Medigap later is different. Outside your guaranteed-issue windows, insurers can usually ask about your health and could charge more or decline you.
6. Stability. Medicare Advantage carriers have left Cheshire County in recent years, and a plan can leave a county at the end of any year. A Medigap policy is guaranteed renewable: the insurer can’t cancel it as long as you pay your premium.
What’s Changed in Cheshire County?
Medicare Advantage. Several carriers stopped offering Medicare Advantage plans in Cheshire County for 2026. For 2027, the New Hampshire Insurance Department reports that Aetna and WellSense are leaving New Hampshire’s Medicare Advantage market.
Medicare Supplement is sold statewide. New Hampshire’s 2026 Guide to Medicare Supplement Insurance lists 22 insurers. Medigap plans are standardized by letter, so a Plan G or Plan N covers the same benefits no matter which insurer sells it. Medigap pricing doesn’t change meaningfully by county. Premiums vary by insurer and age, and the New Hampshire Insurance Department publishes rates so you can compare.
When Can You Buy Medigap Without Health Questions?
Buying a Medigap policy is easiest during a guaranteed-issue window. During these windows, an insurer can’t turn you down, charge you more because of your health, or make you wait for coverage of a pre-existing condition. Under federal rules, they include:

If your Medicare Advantage plan is ending for 2027, don’t cancel anything until you know when your new coverage starts. Guaranteed-issue rights depend on why your coverage is ending, so confirm yours before you make a change.
Why Work With a Local Medicare Agent Who Knows Cheshire County
National call centers often can’t keep up with local network details, like which plans include Cheshire Medical Center in a given year. Gilman Agency is an independent agency with offices in Bedford, Hampstead and Dover, NH, and we help Medicare beneficiaries across the state, including Keene and Cheshire County, by phone and video. We’ll check your doctors, hospital and prescriptions, and walk through Medicare Advantage, Original Medicare, Part D and Medigap with you side by side.
What To Do Next
-
List your doctors, hospital, prescriptions and pharmacy.
-
Decide what matters most: your network, predictable costs, travel, or the ability to switch later.
-
Check your deadlines. Annual Enrollment ends December 7. If your plan is ending, note your Medigap guaranteed-issue deadline.
-
Talk it through. Call Gilman Agency at (800) 927-9326 or email marc@gilmanagency.com. If you would like a licensed agent to contact you about your Medicare options, please complete our Permission to Contact form.
We offer every plan available in your area. Currently we represent 1 organization which offers 1 product in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.
Sources
Medicare.gov (“Compare Original Medicare & Medicare Advantage” and Medigap guaranteed-issue rights); the New Hampshire Insurance Department’s “Medicare Advantage Changes in New Hampshire” (2026 and 2027) and 2026 Guide to Medicare Supplement Insurance (Version 2026-1.2, 05/15/26); and Cheshire Medical Center’s list of insurances accepted.
This article is general educational content, current as of the date above. It is not a recommendation for any specific plan. Carrier participation, networks and premiums can change; confirm details with the plan or at Medicare.gov. Gilman Agency is not affiliated with or endorsed by the U.S. government or the federal Medicare program.


