By Marc Gilman — July 11, 2026
For additional information, please call: (800) 927-9326 or email:
Turning 65 comes with a lot of paperwork and a lot of decisions — but one of them comes with a deadline most people don’t know about. The day your Medicare Part B coverage starts, a 6-month clock begins on the best opportunity you’ll ever have to buy a Medicare Supplement plan. Miss it, and you may have to answer health questions — or be turned down entirely — for the rest of your life.
Here’s what that window is, why it matters so much, and what to know before it closes.
Key Takeaways:
-
Your Medigap Open Enrollment Period is 6 months long, starting the month you’re 65 or older and enrolled in Medicare Part B.
-
During this window, insurers must sell you any Medigap plan they offer, at the best available rate, regardless of your health.
-
Outside this window, most states allow insurers to medically underwrite you — meaning you can be charged more or denied entirely.
-
A Medicare Supplement plan works alongside Original Medicare to cover the deductibles and coinsurance Medicare doesn’t.
-
This window opens once. It does not repeat every year like the Medicare Advantage enrollment period does.
What Is Medicare Supplement (Medigap) Insurance?
A Medicare Supplement — or Medigap — plan is coverage that works alongside Original Medicare (Parts A and B) to pay some or all of the out-of-pocket costs Medicare leaves behind: deductibles, copayments and coinsurance. In 2026, that includes the $1,736 Part A inpatient hospital deductible and the $283 Part B deductible, along with the 20% coinsurance Part B leaves you responsible for on most outpatient services.
Medigap plans are standardized by letter (Plan G and Plan N are among the most popular), so a given plan letter covers the same benefits no matter which insurance company sells it. The difference between carriers comes down to price and service, not coverage.
What Is the Medigap Open Enrollment Period?
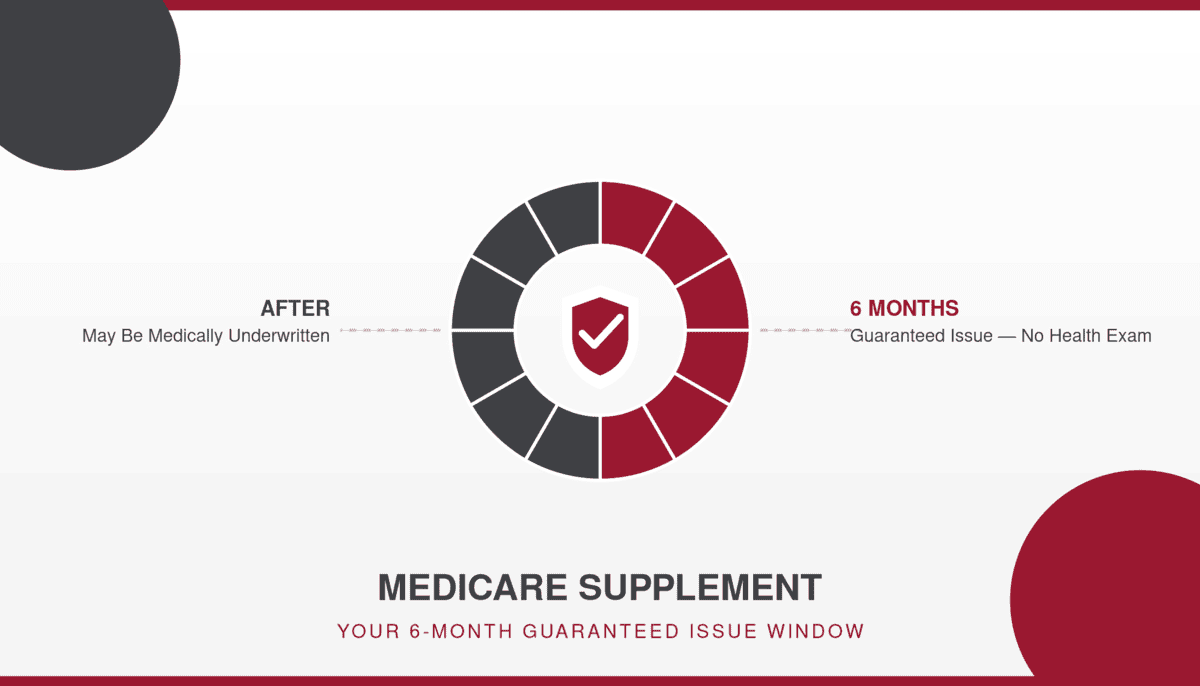
Your Medigap Open Enrollment Period is a one-time, 6-month window that begins the first month you’re both age 65 or older and enrolled in Medicare Part B. It doesn’t reset every year, and it doesn’t come back later — once it closes, it’s closed.
During this window, insurance companies must sell you any Medigap policy they offer, at their best available rate, regardless of your health history. This is what’s known as a guaranteed issue right.
Why Does Guaranteed Issue Matter So Much?
Outside of your Medigap Open Enrollment Period — and outside a handful of other guaranteed issue situations, like losing employer coverage — most states allow Medigap insurers to medically underwrite applicants. That means they can:
-
Charge you a higher premium based on your health
-
Deny you coverage entirely for a pre-existing condition
-
Apply a waiting period before certain conditions are covered
If you develop a health condition after your window closes — something as common as diabetes, heart disease or a cancer diagnosis — you may find yourself unable to get the Medigap plan you want at any price. Buying during your guaranteed issue window sidesteps that risk completely.
What Happens If You Wait?
Some people delay because they’re healthy and don’t feel like they need it yet, or because they want to compare more options first. That’s a reasonable instinct, but it comes with real risk: health can change quickly and without warning, and once your 6-month window closes, you’re relying on the insurer’s willingness — not your right — to sell you a policy.
If you’re enrolling in a Medicare Advantage plan instead and think you might switch to Medigap later, it’s worth knowing that switching back to Original Medicare with a Medigap plan after the fact isn’t guaranteed either, in most states.
How Much Does a Medicare Supplement Plan Cost?
Premiums vary by plan letter, carrier, state and age, but there are two paths worth knowing about:
-
Standard Plan G — comprehensive coverage with no deductible on the plan itself (beyond the Part B deductible)
-
High-Deductible Plan G — the same coverage as standard Plan G, but you pay a $2,950 deductible in 2026 before the plan starts paying, in exchange for a lower monthly premium
Which makes more sense depends on how much you’d rather pay predictably each month versus keep as a lower fixed cost with more exposure if you have a high-cost year.
Which Medigap Plan Is Right for You?
The right plan depends on your health, budget and how much cost certainty you want. But the timing question has one clear answer: if you’re within your 6-month Medigap Open Enrollment Period, it’s worth exploring your options now, while guaranteed issue is on your side — not after a health change forces the question.
Turning 65 or already there? Gilman Agency can walk you through your Medicare Supplement options at no cost, while your guaranteed issue window is still open.
For additional information, please call: (800) 927-9326 or email:
Sources
-
Medicare Interactive, Medigap purchasing details: enrollment periods, guaranteed issue, and more
-
Centers for Medicare & Medicaid Services, 2026 Medicare Parts A & B Premiums and Deductibles
-
Centers for Medicare & Medicaid Services, CY2026 Medigap High-Deductible Options (F, G, J)