
By Marc Gilman
(800) 927-9326 |
Every time you see a long-term care policy described as “tax-qualified,” there’s a specific piece of the tax code making that label possible: IRC Section 7702B. It’s the reason certain LTC benefits come to you tax-free, the reason certain premiums are deductible, and — less obviously — the reason products like recovery care insurance exist as a separate category in the first place.
Key Takeaways:
-
A contract only qualifies under 7702B if it meets a specific list of requirements — coverage limited strictly to qualified long-term care services, no overlap with Medicare, guaranteed renewability, no cash surrender value, and premium refunds that only reduce future premiums or increase future benefits.
-
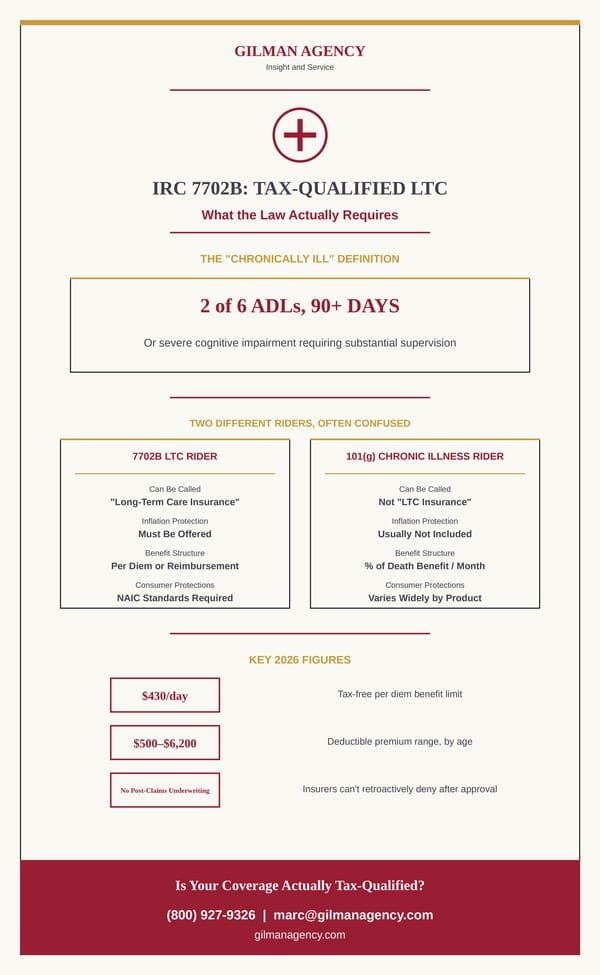
“Chronically ill individual” is precisely defined in the statute itself, not left open to interpretation — certified inability to perform at least 2 of 6 specific activities of daily living for at least 90 days, or severe cognitive impairment requiring substantial supervision.
-
For 2026, qualified LTC benefits are tax-free up to $430 per day under IRS Revenue Procedure 2025-32, with amounts above that (beyond actual qualified expenses) becoming taxable. That limit applies in aggregate across all qualifying policies on the same insured, not separately to each one.
-
Premium deductibility is capped by age, not a flat amount — for 2026, the caps range from $500 (age 40 or under) up to $6,200 (age 71 and older), and only apply if you itemize and your total medical expenses exceed 7.5% of your adjusted gross income.
-
Most popular hybrid life-or-annuity-based LTC products are not tax-qualified in the same way, and their premiums generally aren’t deductible the way a standalone tax-qualified policy’s premiums can be — the statute explicitly denies a deduction for LTC coverage paid for out of a life insurance or annuity policy’s cash value.
-
Qualifying contracts have to meet real consumer protection standards to earn tax-qualified status — no post-claims underwriting, a mandatory offer of inflation protection (even if you decline it), and a required nonforfeiture option if you stop paying premiums.
-
Not every “LTC rider” attached to a life insurance policy is actually 7702B-qualified. Some are structured under a different tax code section (101(g)) as chronic illness riders instead — a related but distinct category that generally can’t be marketed as “long-term care insurance,” often skips inflation protection entirely, and may not satisfy state payroll-tax exemptions that specifically require 7702B-qualified coverage.
What Actually Makes a Policy “Tax-Qualified”?
For a long-term care contract to qualify under 7702B, it has to meet every item on a specific list, not just some of them. The contract can only provide coverage for qualified long-term care services — nothing else can be bundled in as “insurance protection” under the same contract. It can’t pay or reimburse expenses that are otherwise reimbursable under Medicare, or that would be reimbursable but for a deductible or coinsurance amount. It has to be guaranteed renewable, meaning the insurer can’t cancel it because your health declined or because you’ve filed claims. It can’t build up a cash surrender value, and premiums can’t be borrowed against, assigned, or pledged as collateral, aside from narrow exceptions. And if the contract pays out premium refunds or policyholder dividends, that money has to go toward reducing future premiums or increasing future benefits — not into your pocket directly.
Is “Chronically Ill” Actually Defined in the Law?
Yes — precisely, not loosely. The statute itself defines a “chronically ill individual” as someone certified by a licensed health care practitioner as either unable to perform, without substantial assistance, at least two of six specific activities of daily living — eating, toileting, transferring, bathing, dressing, and continence — for a period of at least 90 days due to a loss of functional capacity, or as requiring substantial supervision to protect against health and safety threats due to severe cognitive impairment. That certification has to be renewed at least annually. The law also requires that a qualifying contract’s own certification process take into account at least 5 of those 6 activities when making the determination, not just the 2 the person actually fails.
This is the exact same ADL and 90-day framework that separates a tax-qualified long-term care policy from products like recovery care insurance, which are often deliberately structured outside this definition specifically so they aren’t bound by the 90-day expectation — letting them pay for a condition someone is actually expected to recover from, which a tax-qualified 7702B contract by design excludes.
How Much of My Benefit Is Actually Tax-Free?
For 2026, qualified long-term care benefits paid on a per diem or indemnity basis are excluded from your gross income up to $430 per day, under IRS Revenue Procedure 2025-32 — up from $420 per day in 2025. If your policy pays more than that in a given day and your actual qualified care costs were lower than what you received, the excess above the greater of the two becomes taxable income. Reimbursement-style benefits, which only pay for documented actual expenses rather than a flat daily amount, are generally excluded from income without that same dollar cap, since they’re tied directly to real costs rather than a flat rate.
One detail that matters if you have more than one policy: the statute applies this daily limit in aggregate, not separately to each contract. If you’re receiving qualified per diem payments from more than one policy on the same insured — say, a standalone qualified LTC contract and a life insurance policy paying accelerated benefits for chronic illness — all of those payments are combined and measured against the same single daily cap, not given their own separate limit each. Stacking benefits from multiple policies can push the combined total over the threshold even if each policy on its own would have stayed comfortably under it, so it’s worth checking the math across all your coverage together, not just one policy at a time.
Can I Actually Deduct My Premiums?
Sometimes, and the amount depends entirely on your age, not a flat percentage or dollar figure. For 2026, the maximum amount of qualified LTC premium you can count as a medical expense is $500 if you’re 40 or under, $930 for ages 41–50, $1,860 for ages 51–60, $4,960 for ages 61–70, and $6,200 if you’re 71 or older — figures the IRS adjusts annually for inflation. Even within those caps, you can only actually deduct the amount by which your total itemized medical expenses exceed 7.5% of your adjusted gross income, and only if you itemize instead of taking the standard deduction. Business owners have a real advantage here: premiums a C-corporation pays for an employee’s tax-qualified LTC coverage are generally fully deductible as an ordinary business expense, without being limited by the individual age-based caps that apply to a personal policy. To put a number on it: at a 21% corporate tax rate, $1,000 in premium costs the business roughly $790 after the deduction — the full premium counts, not just a capped portion.
It’s worth being clear-eyed about one thing: most of today’s popular hybrid life-insurance-based or annuity-based LTC products generally aren’t eligible for this premium deduction the way a standalone tax-qualified policy is, even when the LTC benefit itself is paid tax-free under the same 7702B framework. The statute is explicit about this — it specifically denies a deduction for any LTC coverage payment made as a charge against the cash surrender value of a life insurance policy or the cash value of an annuity. That’s a real trade-off against the “nothing is wasted if care is never needed” advantage those hybrid products offer, and it’s written directly into the law, not just an industry convention.
Is Every “LTC Rider” on a Life Insurance Policy Actually 7702B-Qualified?
Not necessarily, and this is one of the more consequential mix-ups in this whole topic. Some riders marketed alongside life insurance are genuinely 7702B-qualified long-term care riders. Others are what’s called a chronic illness rider, governed by a related but different part of the tax code — IRC Section 101(g) — and the two are not interchangeable, even though both can be triggered by the same 2-of-6 ADL or severe cognitive impairment standard.
The practical differences are real. A 101(g) chronic illness rider generally cannot be marketed or sold as “long-term care insurance” — that label is legally reserved for products that actually meet the 7702B standard. Where a 7702B-qualified contract is required to at least offer inflation protection, a 101(g) rider typically doesn’t include it at all, which means the benefit amount can lose real purchasing power over the years before it’s ever used. A 101(g) rider’s benefit is also often structured differently — commonly capped as a percentage of the life insurance death benefit accelerated per month, rather than the per diem or reimbursement structure a 7702B contract uses. And because 101(g) products aren’t required to meet the same NAIC consumer protection standards under 7702B(g), contract language and definitions vary far more from one 101(g) product to the next, making side-by-side comparison genuinely harder.
This distinction is becoming more than academic. Some states considering a payroll tax to fund a public long-term care benefit — Washington’s WA Cares Fund is the clearest example already in effect — allow an exemption for residents who already own qualifying private coverage, but the exemption is generally tied specifically to 7702B-qualified coverage. A 101(g) chronic illness rider, however useful it might be on its own terms, may not satisfy that exemption. If you’re relying on a life insurance rider for this purpose specifically, it’s worth confirming directly which tax code section it’s actually built under, not just assuming any rider that mentions chronic illness or long-term care qualifies the same way.
What Consumer Protections Does 7702B Actually Require?
Being tax-qualified isn’t just about tax treatment — the statute also requires a contract to meet a specific set of consumer protection standards before it can qualify at all. Three of these are worth knowing about directly. First, insurers are prohibited from post-claims underwriting, meaning they can’t retroactively dig through your medical history to deny a claim after you’ve filed one, the way they could before you were approved. Second, a qualifying contract has to at least offer inflation protection as an option — you can decline it, but the insurer has to make the offer and get a proper signed rejection if you turn it down, rather than simply leaving it off the table. Third, insurers have to offer a nonforfeiture provision, so that if you stop paying premiums, you don’t necessarily lose everything — the contract has to offer some form of reduced paid-up coverage, extended term coverage, or a shortened benefit period instead of a total loss.
None of these protections make a specific policy a good deal on their own, but they set a real floor that non-qualified products aren’t required to meet in the same way.
Where Does Insurance Planning Fit In?
Whether a policy is 7702B tax-qualified affects more than just paperwork — it shapes what conditions trigger your benefits, whether your premiums have any shot at being deductible, and how much of your benefit actually arrives tax-free. None of that is obvious from a policy’s marketing materials alone, and it’s exactly the kind of detail worth confirming directly rather than assuming based on a product category’s general reputation.
What To Do Next
If you want to understand whether a policy you’re considering — or one you already own — is actually tax-qualified under 7702B, and what that means for your specific tax situation, we’re glad to walk through it with you. Call us at (800) 927-9326 or email — no pressure, just straight answers.
By Marc Gilman, Gilman Agency
This information is general in nature and not intended as tax or legal advice. Tax rules, dollar limits, and deduction thresholds are set annually by the IRS and are subject to change. Consult your tax advisor regarding your specific situation.
Sources: 26 U.S.C. § 7702B (Internal Revenue Code, full text via Cornell Legal Information Institute and Athena Tax); Treasury Regulation § 1.7702B-1 and § 1.7702B-2; Internal Revenue Service, Revenue Procedure 2025-32; Internal Revenue Service, Instructions for Form 1099-LTC; American Association for Long-Term Care Insurance (AALTCI), 2026 tax-deductible limits announcement; Marc Glickman, FSA, CLTC, “7702(b) or Not to Be: Why 7702(b) Matters for Long-Term Care Planning,” BuddyIns.


